

Thailand Property Market in 2026: Why Buyers Are Looking Beyond Bangkok


Thailand’s property market in 2026 is not moving in one direction. Bangkok remains the country’s main urban residential market, but buyers are becoming more selective and increasingly comparing the capital with resort and lifestyle destinations. Phuket, Koh Samui and Hua Hin are no longer viewed only as holiday-home markets. For some international buyers, they now compete for long-stay living, second homes and income-producing property. This is less a retreat from Bangkok than a broadening of the locations buyers are prepared to consider.
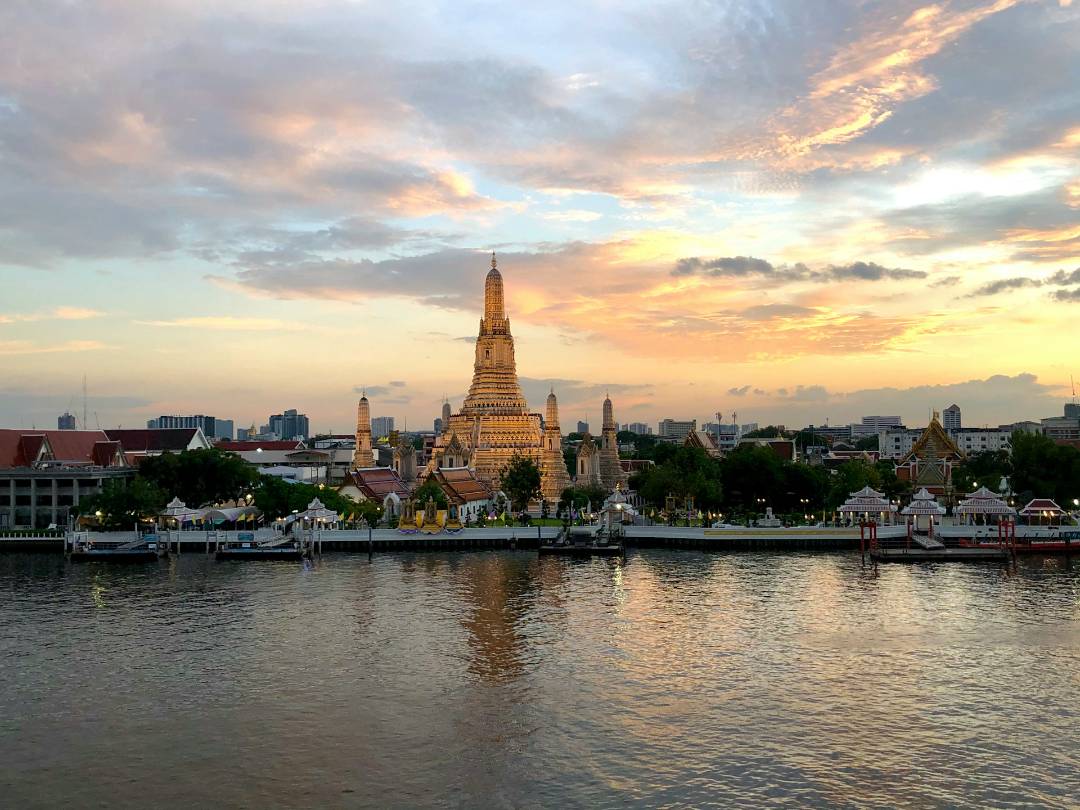
Bangkok Still Matters, but the Market Is More Selective
The shift does not mean Bangkok has lost its appeal. CBRE Thailand’s 2026 outlook shows continued strength in the downtown luxury and super-luxury condominium segment. CBRE reported a 93% sales rate for existing supply, while completed luxury and super-luxury projects in Q1 2026 recorded sales rates of 95% and 86%.
The broader market is more cautious. Knight Frank reported that the sales rate for newly launched Bangkok condominiums fell to 24.3% in Q1 2026, encouraging developers to focus more on city-fringe and suburban locations and accessible price points. Official data from the Real Estate Information Center (REIC) adds context: in Bangkok and its surrounding provinces, residential ownership transfers rose 10.5% year-on-year in Q1 2026, but their total value fell 2.8%, while new units launched for sale dropped 31.1%.
Foreign Demand Is Broad, but Not Uniform
REIC recorded 3,241 condominium transfers to foreign buyers nationwide in Q1 2026, down 17.3% year-on-year, with a total value of THB 13.46 billion, down 17.9%.
The 2025 provincial distribution also shows how demand extends beyond Bangkok and is no longer concentrated only in the capital. REIC recorded 7,029 foreign condominium transfers in Bangkok, but also 1,190 in Phuket, 491 in Prachuap Khiri Khan, which includes Hua Hin, and 212 in Surat Thani, which includes Koh Samui.
Phuket Is Becoming a Full-Time Lifestyle Market
Phuket is the clearest example of the change. Colliers describes the island’s residential market as entering a renewed expansion phase, supported by tourism, international buyers and stronger developer confidence. Villa demand is increasingly connected to low-density, lifestyle-driven living rather than short holiday use alone.
FazWaz data points to a broad international demand base. Its 2026 Phuket analysis recorded 54,628 buyer and tenant enquiries between December 2025 and May 2026, with 62% originating overseas and 71% relating to rentals. That mix matters because a deep rental market can support both investors and buyers who want flexibility before committing to full-time residence.
Official tourism indicators reinforce the southern market’s appeal. Bank of Thailand data show accommodation occupancy in southern Thailand at 80.4% in January 2026 and above 72% in May. Strong visitor flows do not guarantee property returns, but they support rental demand, services and year-round amenities.
For international buyers comparing premium villas and residences outside the capital, Private Office Property can simplify the search with a curated selection of luxury real estate in Phuket and Koh Samui, plus support for purchase, rental and property management. The value of specialist guidance becomes more important as coastal markets differ sharply by neighbourhood, ownership structure, project quality and management model.
Samui and Hua Hin Offer Different Alternatives
Koh Samui appeals to buyers who prioritise privacy, sea views and lower-density villa living. Colliers reported that villa supply increased 34% year-on-year in the first half of 2025, while take-up improved to 71.5%. In a smaller market, buyers should pay close attention to access, utilities, construction quality, management and resale liquidity rather than relying only on headline yields.
Hua Hin offers a different proposition. Its proximity to Bangkok makes it practical for domestic travel while providing a quieter coastal lifestyle and, in many cases, a lower entry point than prime Bangkok or Phuket. For retirees, families and long-stay residents, healthcare, schools, daily services and established communities may matter as much as beachfront proximity.
What Buyers Should Compare Beyond the Purchase Price
Looking beyond Bangkok only makes sense when the property matches the buyer’s objective. A holiday villa, a long-term residence and a rental investment require different criteria. Buyers should compare local rental demand, seasonality, developer track record, maintenance costs, property management, resale depth, infrastructure and realistic net yield after expenses. Foreign purchasers should also obtain independent legal advice on ownership structure, land rights, contracts and due diligence before committing funds.

Another important distinction is supply type. Bangkok investors often compare standardized condominium units with established resale benchmarks, while island buyers may be evaluating villas with highly individual land plots, views, access roads and management arrangements. That makes property-level due diligence and conservative exit assumptions especially important in resort markets.
A More Diversified Thailand Property Map
The defining 2026 trend is therefore not a simple move away from Bangkok. It is a more diversified property map. Bangkok remains central for urban luxury and liquidity, while Phuket, Samui and Hua Hin offer different combinations of lifestyle, space and international demand. Buyers who compare these markets on verified fundamentals rather than marketing headlines are better placed to choose a location that fits both how they want to live and how they expect the property to perform over time.
